Türkiye’s ambition to become a regional fintech hub will not only attract greater investor interest but also accelerate the digital transformation journeys of businesses ranging from SMEs to large enterprises. At Octet Türkiye, we are positioned at the heart of this transformation. Through our B2B payment and collection solutions, we streamline financial processes for businesses while contributing to the development of the broader ecosystem.
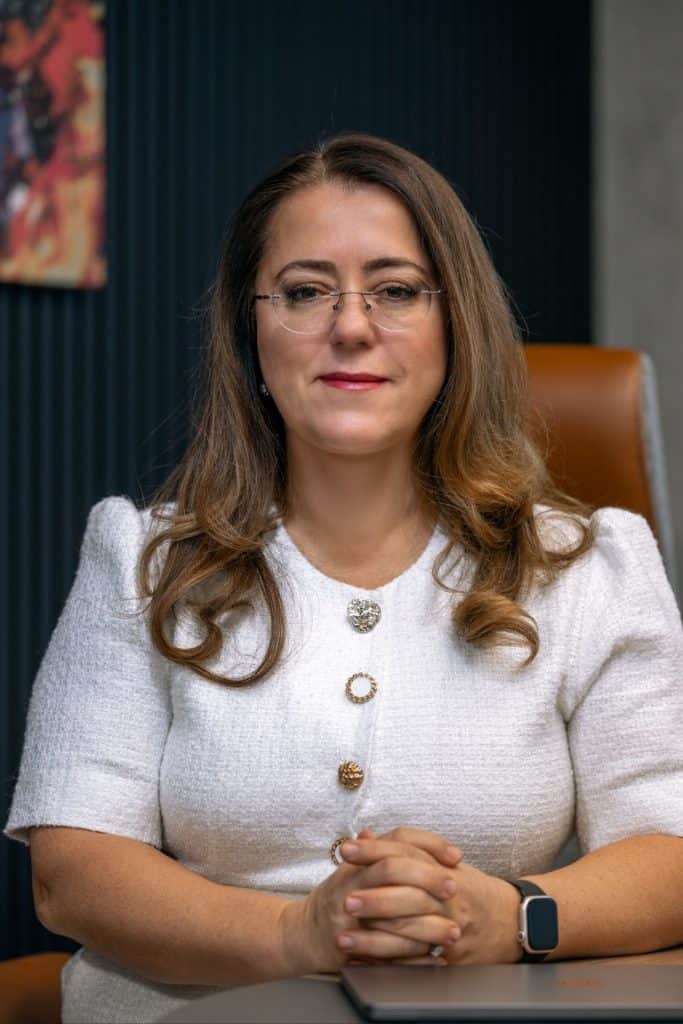
Derya Ekemen Fidan, CEO of Octet Türkiye
As a leader who has held senior roles in banking and financial technologies for years, how would you summarize the digitalization process in payments, collections, and money transfers?
The digitalization of payments and collections has fundamentally transformed corporate financial processes. Today, there are 117 million active digital banking customers in Türkiye, approximately 4.6 million of whom are corporate digital users. Considering that there are nearly 1.5 million active incorporated companies in Türkiye, according to the Ministry of Trade and TOBB data, this figure clearly demonstrates how strongly businesses have integrated into financial digitalization.
Processes that were once manual, lengthy, and complex have evolved into real time, traceable, and fully integrated flows through instant payment systems (FAST) and API based integrations. Businesses can now complete payments and collections within seconds, monitor cash flow in real time, access financing more quickly, and achieve up to a 30 percent improvement in cash flow visibility.
Bank fintech collaborations provide financial flexibility through alternative payment and collection channels, while open banking accelerates secure data sharing. Particularly in the B2B space, guarantee, mandate, and assessment processes are becoming increasingly digital, secure, and efficient.
All of these developments clearly show that financial technologies have become an integral part of everyday business life.
What does the future hold for digitalization in payment and collection solutions? What do you see as the critical priorities for the sector?
In the near future, managing and interpreting data in payment and collection solutions will become equivalent to managing money itself. The financial ecosystem is rapidly evolving toward a real time, data driven, and customer centric structure. Instant analytics and fast decision making mechanisms will increase collection speed while strengthening cash flow management.
According to 2024 data, the total volume of digital payments in Türkiye exceeded TRY 3.2 trillion. Over the next five years, 70 percent of this volume is expected to be processed through digital channels. Mobile wallets, QR codes, and contactless payments are becoming standard in everyday life, while speed, security, and transparency are emerging as the most critical components of customer experience.
Advanced technologies will also enable the use of data to anticipate customer behavior and develop new business models. Artificial intelligence will play a pivotal role in fraud detection and risk management, while regtech solutions and compliance frameworks will be essential in building trust. As trust becomes as important as technological innovation, sustainable finance approaches and inclusive business models will be key to the healthy growth of the fintech ecosystem.
How do you evaluate Türkiye’s journey toward becoming a regional fintech hub?
Türkiye’s fintech ecosystem has gained significant momentum in recent years. As of 2024, there are 901 fintech startups in the country, 731 of which are actively operating. Fintech investments reached 194 million USD in the same year. These figures demonstrate that Türkiye is rapidly advancing not only as a local player but also as a strong regional contender.
Investments across digital banking, payment institutions, open banking applications, and AI based solutions reinforce Türkiye’s ambition to become a regional hub. A young, technology integrated population and proactive regulatory initiatives are among the strongest drivers of this journey.
Becoming a regional fintech center will not only increase investor interest but also accelerate digital transformation across a broad business base, from SMEs to large enterprises. At Octet Türkiye, we are at the center of this transformation, enhancing financial processes through our B2B payment and collection solutions while contributing to ecosystem development.
Could you briefly summarize the solutions Octet Türkiye offers?
Our approach is built on delivering end to end payment and collection solutions in the B2B segment.
On the collection side, we offer Virtual POS, Direct Debit System (DBS), Request to Pay, and NFC based collection products. Our Virtual POS accelerates both collection and payment processes while creating value in working capital management. Through DBS, sellers can view and verify buyers’ credit limits without opening accounts at multiple banks, secure their receivables, and collect payments on maturity through Octet. Request to Pay enables 24/7 cash collection via the Octet Platform, while our NFC enabled Octet Mobile application digitalizes collection processes and simplifies workflows.
On the payment side, our solutions include the Supplier Financing System and Master Merchant model. With Supplier Financing, buyers can manage working capital and balance sheets more efficiently. Through Master Merchant, buyers can extend payment terms and create more flexible cash flow structures.
In short, we enable businesses to manage both collections and payments in a secure, fast, and fully digital end to end structure.
Could you share Octet Türkiye’s transaction volumes and growth trajectory over the years?
In 2023, our transaction volume stood at TRY 27 billion. By the end of 2024, it exceeded TRY 55 billion. Our transaction count reached 305,000, with the average transaction size increasing to TRY 183,000. Today, we serve more than 7,500 customers, 50 percent of whom are SMEs.
Our goal is to surpass TRY 100 billion in transaction volume in the coming period. We aim to achieve this growth not only in scale but also in a sustainable manner, with a strong focus on customer experience.
What new investments and innovations can we expect from Octet Türkiye?
In the coming period, we plan to prioritize investments in artificial intelligence and data analytics. Our objective is to further enhance customer experience, maximize operational efficiency through next generation technologies, and develop innovative solutions accordingly.
At the core of our vision is delivering scalable, customizable services tailored to the needs of different industries. We also see significant opportunities in open banking and plan to deepen our investments in this area to create greater value within the ecosystem.
Beyond artificial intelligence, which technologies are shaping the digitalization of payment methods? How does Octet Türkiye integrate them?
As in many industries, artificial intelligence and machine learning are leading technologies in the digitalization of payment methods. In addition, cryptography, network tokenization, and ISO 20022 based global data processing standards are increasingly important.
Global players leverage these technologies to accelerate cash conversion cycles, scale internationally, prevent fraud, and improve user experience.
At Octet Türkiye, we place the digitalization of finance at the center of our strategy. We redesign operational processes through secure and innovative technologies. With every step we take, we develop solutions that ease cash flow management for B2B companies while creating measurable value for our clients and helping shape the future of the sector.